What it costs to own a home in New York, NY
The median homeowner with a mortgage in New York, NY spends about $3,232 a month to keep the house, of which property taxes are about $9,937 a year. That is the full cost of owning, not just the loan payment. It includes the mortgage, property taxes, insurance, utilities and any HOA fees. It decides whether staying is affordable, and it is the number people underestimate when they buy.
US Census Bureau, American Community Survey 5-year estimates averaging 2019 to 2023. They show the usual cost of owning here, not this month.
- Monthly, with a mortgage
- $3,232
- Monthly, mortgage paid off
- $1,297
- Property taxes
- $9,937/yr
- Spending over 30% of income
- 37.1%
All in: loan, taxes, insurance, utilities
What ownership costs with no loan at all
Median for the metro
Of 2,336,800 mortgaged households
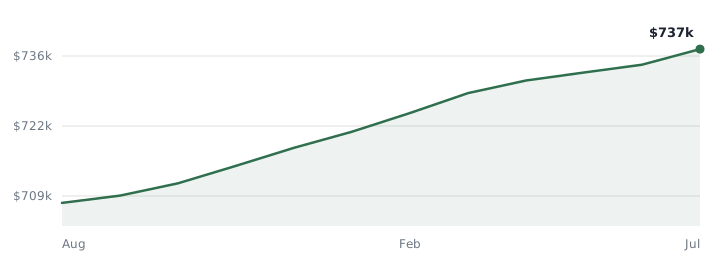
How many people here are stretched
About 37.1% of New York homeowners with a mortgage spend more than 30% of their household income on housing. HUD and the Census Bureau call a household cost burdened once housing takes more than 30% of income. That is where housing starts crowding out everything else. Roughly 2,336,800 households here carry a mortgage. That is a high share by national standards, and it is the math behind a lot of the calls we get. When a third of mortgaged owners are already stretched, it takes very little to tip a household over. An insurance renewal, a tax reassessment, a roof or one lost income can do it.
Across the 100 largest metros we track, that is the 7th highest share of stretched homeowners. Property tax is an unusually large part of that. About 26% of what a New York owner pays in a year goes to the tax bill, so a higher assessment hits harder here than in most places. Every nearby market we track is cheaper to hold, including Bridgeport at $3,196 and New Haven at $2,342.
On the other half of the picture, houses in New York take about 55 days on average to go under contract. So even where a normal sale is the right answer, it is not a quick fix for a monthly cost problem.
The house with no mortgage on it
Owners in New York who have paid off the mortgage still spend about $1,297 a month, compared with $3,232 for owners still paying one. That money goes to taxes, insurance, utilities and upkeep, and it does not stop when the loan does. So an inherited house with no mortgage can still cost more than the family can afford to keep. "There is no mortgage" is not the same as "there is no hurry".
What actually pushes the number up
The monthly figure above is a median across New York, NY. Medians hide what causes trouble: these costs do not move together, or predictably.
- Insurance. The most volatile cost, and the one least tied to what you paid for the house. It is a smaller pressure in New York than in coastal and wildfire-prone markets. But a renewal can still jump by a large percentage in one year, even if nothing about the house changes.
- Reassessment. Property tax follows assessed value. A sale, an improvement or an area-wide revaluation can reset it well above the $9,937 median. Inheriting a long-held house often triggers exactly this. In New York the tax bill alone is about 26% of the yearly cost of holding the property.
- Deferred maintenance. Not in any of these figures. A roof, a furnace or a sewer line comes as one big bill, not a monthly one. It is usually what turns a manageable house into one you cannot keep up with. A single $15,000 repair is about 5 months of everything else a New York owner pays.
- Income, not cost. Cost burden is a ratio. A retirement, a divorce or a lost job moves it just as sharply as a rising bill, with no change to the house. At $3,232 a month, a New York household needs about $129,000 a year to stay under the 30% line. Losing a second income is usually what pushes a household over it, not a change in housing costs.
If keeping it no longer works
Nothing on this page says you should sell. Most people with high housing costs should not. First try refinancing, appealing an assessment, shopping for new insurance, or adding income. Those cost less than taking a discount on the biggest thing you own.
Selling to a cash buyer makes sense when those routes are closed and a normal sale is closed to you too. Maybe the house needs work you will not pay for, a tenant is in place, or it is full of a parent's belongings. Or something other than your choice sets the timeline. That is the narrow case where we actually help.
For what a normal sale would involve here, see how long it takes to sell a house in New York. For the market as it stands this month, see our New York page.
Common questions
- How much does it cost to own a home in New York?
- About $3,232 a month for the median owner with a mortgage. That covers the loan, property taxes, insurance, utilities and any HOA fees. Owners who have paid off the mortgage still spend about $1,297 a month on everything else. Census figures averaging 2019 to 2023.
- How much are property taxes in New York?
- The median household pays about $9,937 a year. That is a median for the whole metro, so a pricier house pays more. A reassessment after a sale or an improvement can also move it sharply. Your own bill is the one that matters, and it is public record.
- Is New York an expensive place to keep a house?
- By the measure that matters most, yes. About 37.1% of mortgaged owners here spend over 30% of income on housing, which is high for a US metro. This compares local costs with local incomes, not the price of the houses. A cheaper market with lower wages can be harder to afford than an expensive one.
- What does "cost burdened" mean?
- Housing costs above 30% of household income. That is the line HUD and the Census Bureau use. In New York about 37.1% of owners with a mortgage are above it.
- I own my house outright. Why would I ever need to sell?
- Because taxes, insurance and upkeep do not stop when the mortgage does. Owners here with no mortgage still spend around $1,297 a month. On a fixed income, or with an inherited house nobody lives in, that cost is often why a family sells. It has nothing to do with a lender.
- Are these figures current?
- No, and that matters. They come from the Census Bureau's American Community Survey 5-year estimates, which average 2019 to 2023. They are reliable for how owning here compares with other places. But they will not catch a recent jump in insurance or taxes. The market figures on our New York page are separate and refresh monthly.
Source: U.S. Census Bureau, American Community Survey 5-year estimates, 2019-2023. Tables B25088, B25091 and B25103. Figures are metro-wide medians and describe no individual property.
Tell us what you need for your New York house
You do not need a number ready, or photos, or a plan. Want to know your real options, even the ones that do not involve us? Call and ask.
Sabrina usually picks up. (615) 576-8827